PayCredit Credit Chargebacks
Credit Chargebacks
When your customer disputes a credit card transaction, PayCredit applies the relevant financial adjustments to their credit account.
PayCredit does not investigate disputes, collect evidence or determine their outcome. These activities are managed separately, either through Paymentology Disputes & Chargebacks or through your own or a third-party dispute management system.
PayCredit uses the dispute information and final outcome to adjust the customer's credit account based on the programme configuration and the transaction's credit lifecycle stage.
How chargeback processing works
The chargeback ecosystem brings together scheme processing, dispute management and credit account financial processing.
| Component | What it handles |
|---|---|
| Paymentology scheme processing | Supports Mastercard FAST 1442 chargeback intake across Paymentology clients, regardless of who manages disputes. |
| Paymentology Disputes & Chargebacks | A separate application and service that manages operational disputes when Paymentology is selected to manage them. |
| Client or third-party dispute system | Manages dispute investigation and resolution when you use your own dispute management process. |
| PayCredit | Calculates and applies the relevant principal, interest, fee, balance, available-credit and delinquency adjustments to the credit account. |
Follow a chargeback from start to finish
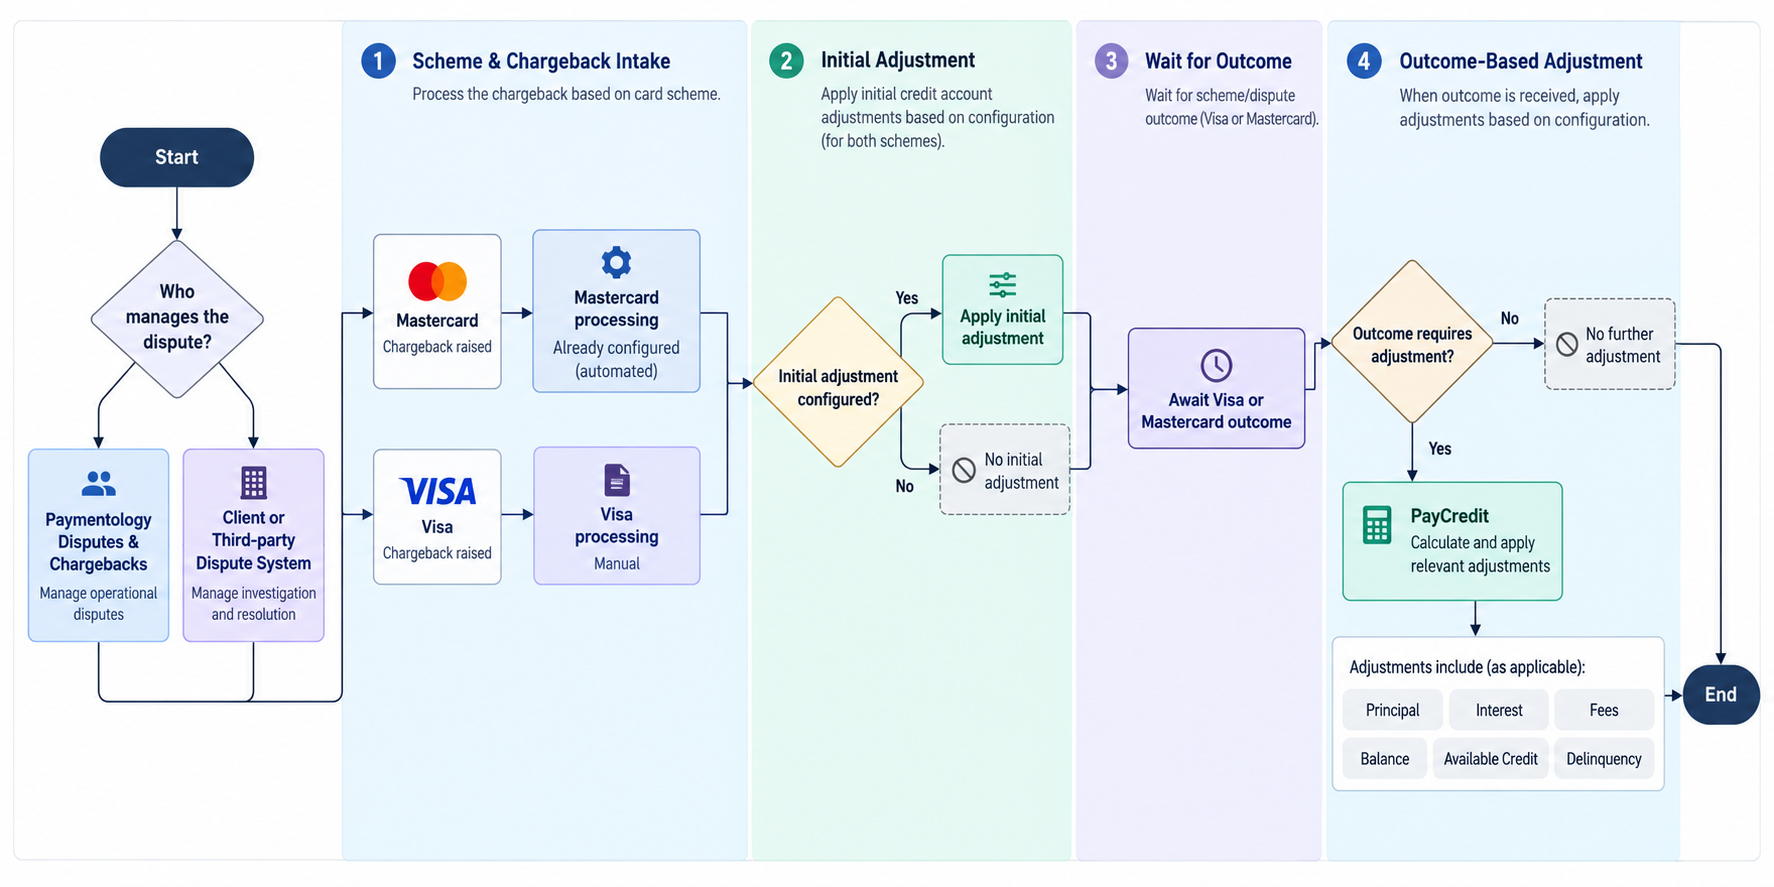
Consider a customer who disputes a settled credit card purchase of £100.
The following flow shows how the dispute moves from the operational process to the financial adjustments in PayCredit.
-
The customer raises a dispute.
The dispute is managed by Paymentology Disputes & Chargebacks, your team or your third-party provider, depending on your operating model.
-
Dispute information reaches PayCredit.
For Mastercard, supported FAST 1442 processing receives the chargeback information, matches the original transaction and automatically creates the dispute in PayCredit.
For Visa, dispute information is provided through Paymentology Operations or the supported client integration, depending on the operating model.
-
PayCredit applies the initial financial treatment.
PayCredit evaluates the transaction's lifecycle stage and the programme's Direct Chargeback Credit setting.
Eligible settled disputes may receive provisional financial relief while the dispute remains open.
-
The operational dispute is resolved.
The dispute outcome is determined through the relevant operational dispute process and recorded in PayCredit.
The outcome may be a customer win, merchant win or partial win.
-
PayCredit applies the final financial treatment.
PayCredit calculates and posts the applicable credit account and ledger adjustments based on the final outcome, programme configuration and transaction lifecycle stage.
Choose how operational disputes are managed
You can use Paymentology Disputes & Chargebacks or manage disputes through your own or a third-party system.
The choice determines who manages the operational dispute and who provides the final outcome to PayCredit.
| Operating model | Who manages disputes? | What your team needs to do |
|---|---|---|
| Paymentology-managed | Paymentology Disputes & Chargebacks team manages the operational dispute process. | Agree the programme configuration and operating arrangements. Paymentology Operations handles dispute creation and final outcome recording where applicable. |
| Client-managed | Your own dispute management system manages investigation and resolution. | Provide the required dispute information and final outcomes through the supported integration or operating process. |
| Third-party managed | Your selected dispute provider manages investigation and resolution. | Arrange for the required dispute information and final outcomes to reach PayCredit through the agreed integration or operating process. |
In all three models, PayCredit applies the relevant financial calculations and credit ledger adjustments, automatically
What does PayCredit handle automatically?
Once PayCredit receives the required dispute information, it applies the relevant financial treatment according to the programme configuration and transaction lifecycle stage.
This can include:
- Applying provisional credit to eligible settled disputes when enabled.
- Adjusting disputed principal and available credit.
- Calculating applicable interest and eligible fee adjustments.
- Updating applicable statement balances and payment obligations.
- Applying the relevant delinquency treatment.
- Calculating and posting final financial adjustments after dispute resolution.
The exact financial treatment depends on whether the transaction has settled, been billed or already been paid, and whether the dispute is upheld, rejected or partially upheld.
Get started
Follow these guides to complete your chargeback implementation.
| Guide | What you will accomplish |
|---|---|
| Set Up Chargeback Processing with PayCredit | Understand which scheme processing capabilities are already available, configure provisional credit and complete the integrations required for your dispute management model. |
Start with Set Up Chargeback Processing with PayCredit to identify the configuration and integration activities required for your programme.
Updated 21 days ago